The short answer
Supplier payment finance helps a business pay eligible supplier invoices, then repay a finance provider over agreed terms. It is borrowing for bills you owe, rather than an advance against invoices your customers owe you.
How supplier payment finance works
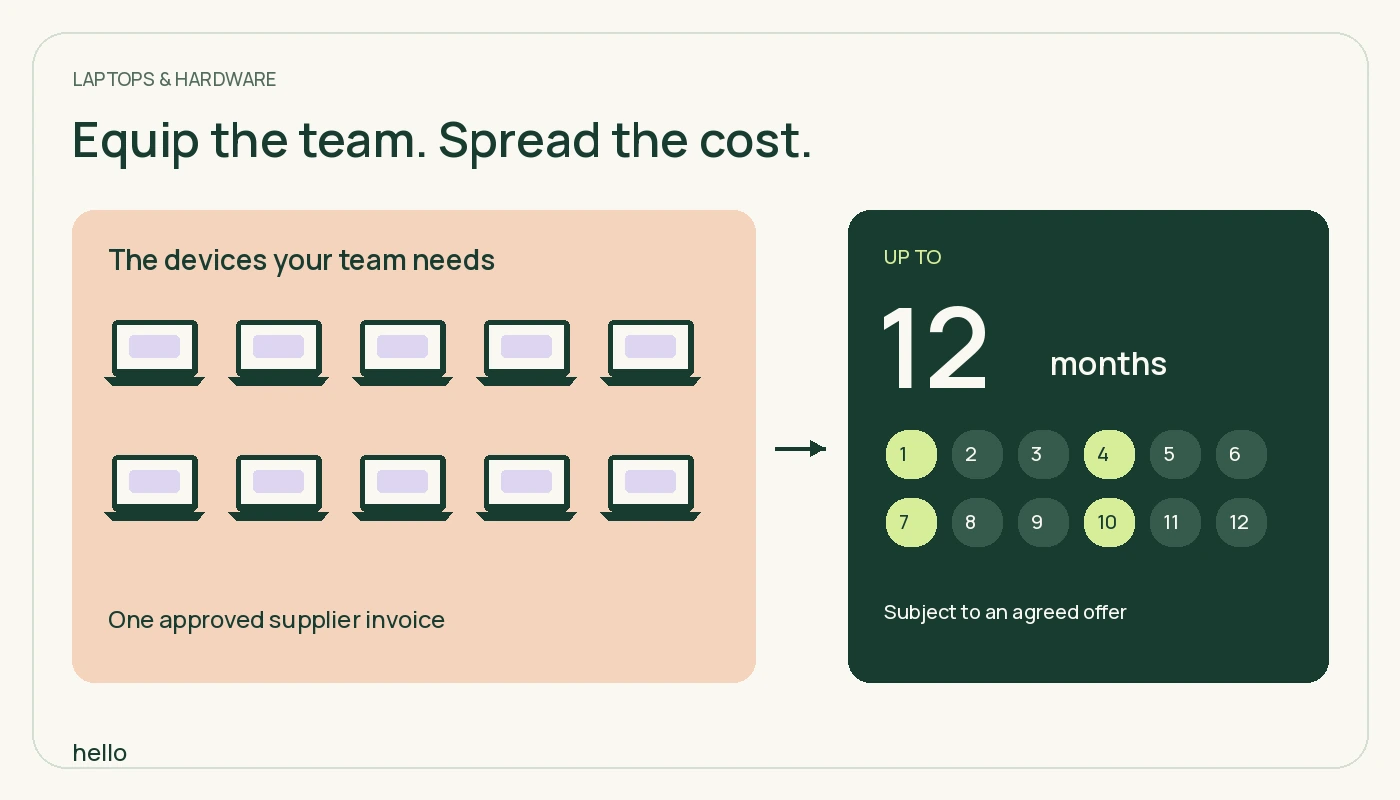
The arrangement starts with an approved facility and an eligible bill. Subject to the provider’s checks and terms, the supplier receives payment and your business takes on a repayment obligation. The facility does not remove the cost of the purchase; it changes when cash leaves your business.
- Identify the payment. Check the invoice amount, due date, supplier details and purpose of the purchase.
- Understand the offer. Confirm the total cost, payment dates, security and any personal guarantee before accepting.
- Pay the supplier. Follow the provider’s approval and payment process. Do not promise a supplier a payment date until it is confirmed.
- Repay from business cash flow. Keep the scheduled repayments in your forecast alongside existing obligations.
A cash-flow example: a £30,000 supplier bill
Imagine a wholesaler with a £30,000 stock invoice due now. It expects to sell the stock over the next three months. Paying the entire invoice from cash today would leave less room for wages, rent and delivery costs.
This simplified split excludes all finance charges and assumes equal principal repayments. Actual payments, fees, timing and availability depend on the agreement.
The useful question is not simply whether the business can obtain £30,000. It is whether the expected cash receipts can cover the scheduled repayments and normal trading costs. If sales arrive a month late, the repayment dates may still stay the same.
Seven questions to ask before accepting finance
- What exact amount will be paid to the supplier, and when?
- What is the total amount my business must repay, including every fee?
- When is the first payment, and what is the complete schedule?
- Is the facility committed, or can further funding be reduced or withdrawn?
- What security or personal guarantee is required?
- What happens if I repay early, miss a payment or dispute the supplier’s invoice?
- Can the facility sit alongside my existing borrowing, and are any consents required?
Ask for the answers in writing. An attractive monthly figure can be difficult to compare if it leaves out an upfront fee, a final payment or a minimum charge.
How it differs from other ways to pay suppliers
Supplier credit means agreeing payment terms directly with the supplier. Invoice finance releases money against eligible invoices owed by customers. In a traditional supply chain finance programme, a buyer’s approved invoices can support earlier payment to participating suppliers.
Names are sometimes used loosely. Start by asking whose invoice is being financed, who receives the money and who must repay. Our supplier finance versus invoice finance comparison explains the difference in more detail.
What to prepare for an application
Write down the payment you want to make, the date it is due and the source of the cash you expect to use for repayments. Bring a forecast that includes tax, payroll, existing debt and a slower-sales scenario. The provider will confirm which accounts and supporting information it needs.
Hello Supplier Finance makes introductions for established UK limited companies and LLPs with £1 million or more in annual revenue. Our introduction is free. Eligibility, lending decisions and finance charges are determined by the provider. An introduction is not an approval.
You do not need to put financial documents into our initial enquiry form. It asks for four contact details to handle your enquiry. We identify the proposed provider privately before asking permission to share your enquiry.
Questions, answered.
Is supplier payment finance a grant?
No. It creates a repayment obligation. The finance provider will explain charges and any security or guarantee requirements.
Does an introduction affect my credit score?
An enquiry to Hello Supplier Finance is not a lending application and this website does not perform a credit search. Ask the provider which searches it will make before submitting a full application.
Can I use finance for every supplier bill?
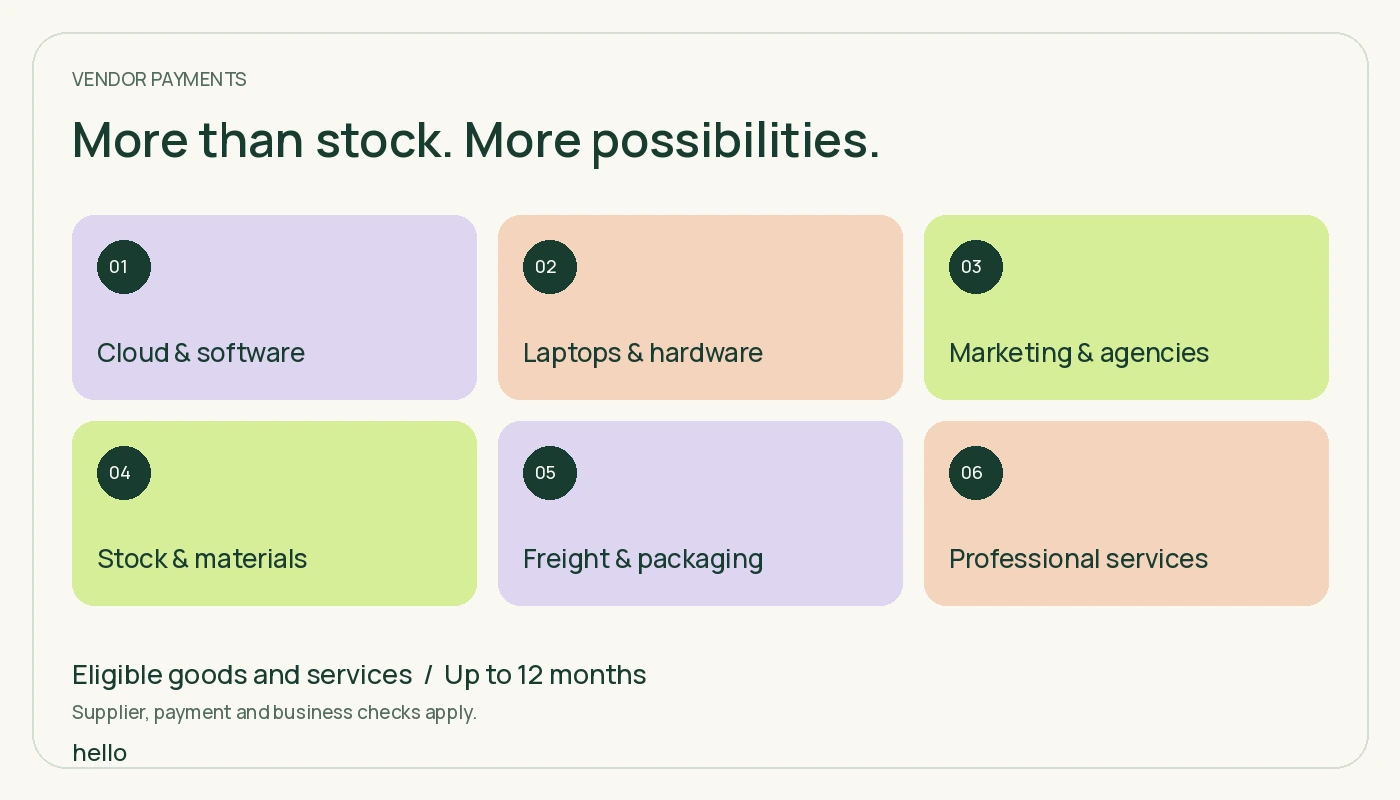
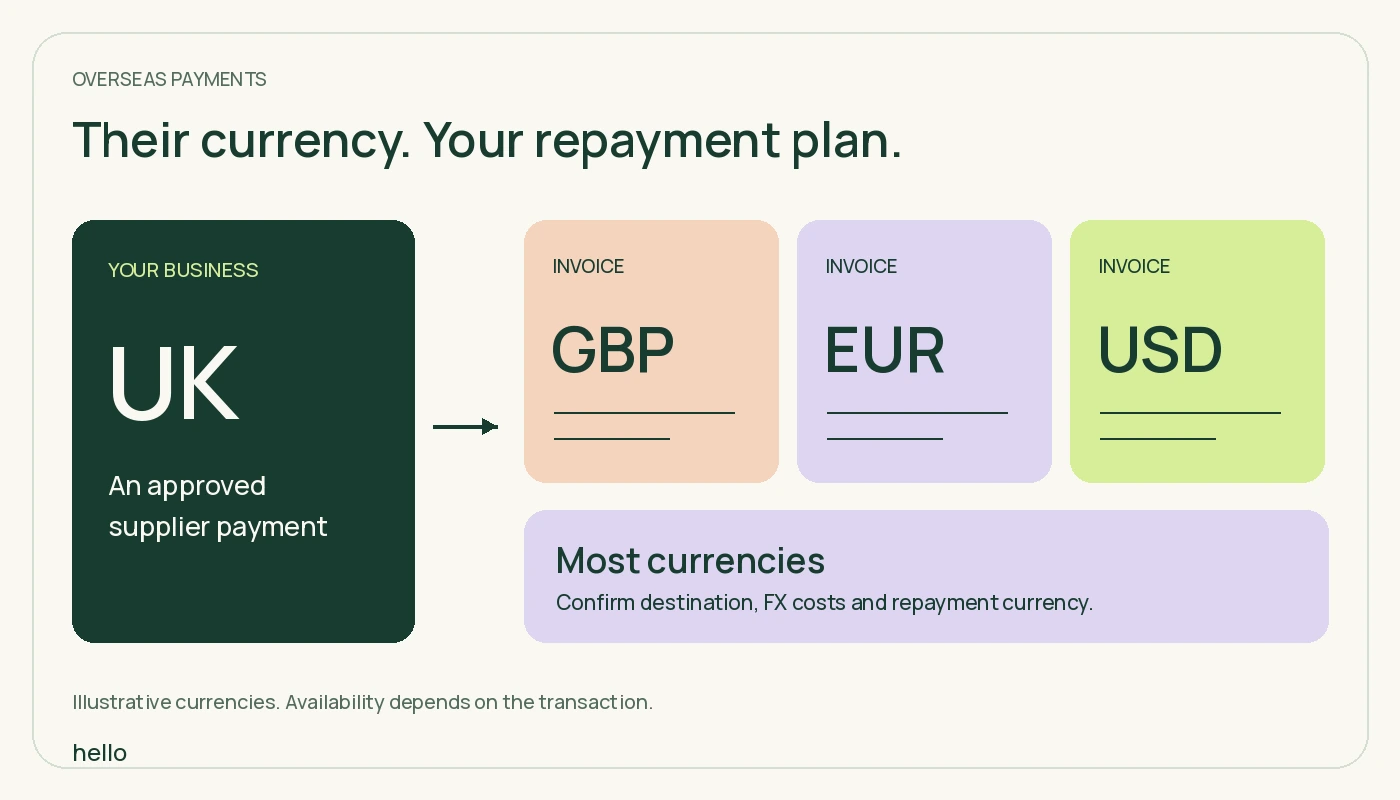
Do not assume every invoice is eligible. Ask the provider to confirm supplier, purpose, currency, location and payment restrictions.
Sources and scope
General background sources, checked 16 October 2026. Examples and planning checklists are our own illustrations.
This guide is general information, not tailored financial advice. Finance availability and terms depend on the provider’s assessment. Consider independent advice before committing.